
Financial Planning Is Becoming the Growth Engine for Firms
Wealth management professionals are facing pressure on multiple fronts. While practices and firms encounter a wide range of challenges as… Read More


Insights and best practices for successful financial planning engagement
• Melanie McConville, RCC • September 22, 2026
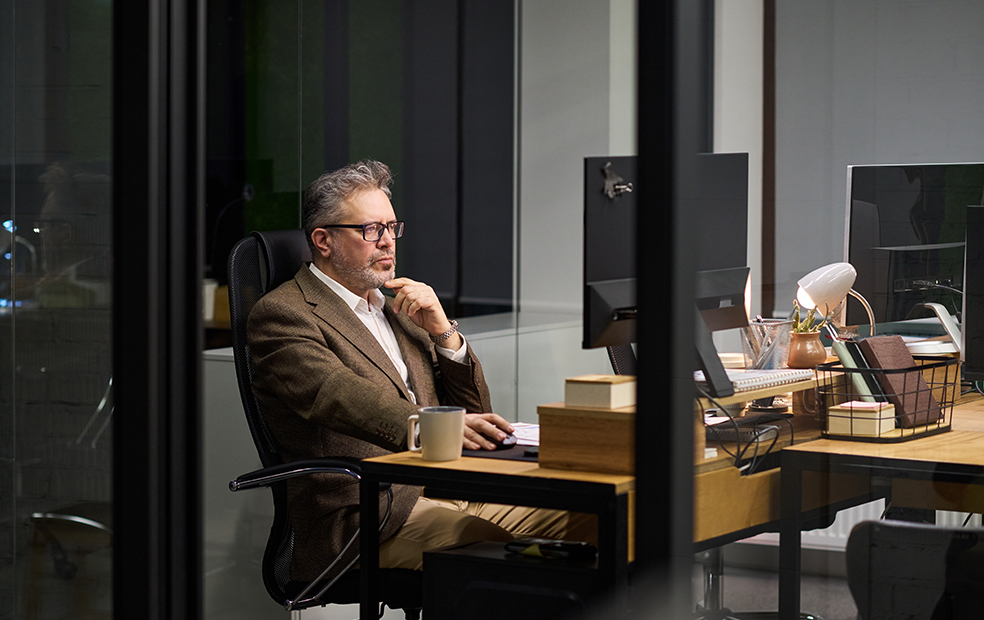
Editor’s Note: This article is the first in a two-part series exploring what happens when successful financial professionals become business owners and team leaders. In Part 1, Melanie McConville examines the signs that an advisor has outgrown the solo-practice mindset and why sustainable growth starts with rethinking the business itself.
Most financial professionals don’t set out to become CEOs.
They start by doing what they love: helping clients navigate financial decisions, building trusted relationships, and serving as a steady source of guidance through life’s milestones. Over time, many establish thriving practices through expertise, hard work, and an unwavering commitment to client service.
Then something unexpected happens.
The business grows to a point where technical expertise is no longer the only driver of success. The challenge is no longer simply finding clients or serving them well. The challenge becomes building a business that can serve clients consistently without depending on one person to do everything.
I often call this the “accidental CEO” stage. It’s the point where an advisor realizes they are no longer just managing client relationships. They’re leading a business.
The first sign that a business has reached this point often isn’t operational. It’s emotional.
When advisors reach this stage, the warning signs rarely appear first on a profit-and-loss statement or a business dashboard. Instead, they feel it.
In coaching conversations, I often hear advisors describe the sensation as being overwhelmed, stretched too thin, or simply unable to keep up. They’ve spent years working at full capacity, solving problems by working harder and putting in more hours. But eventually, they discover there is no more room to give.
One advisor described it as feeling like they couldn’t breathe.
That feeling can be a signal that the business has outgrown the way it’s being run.
Onboarding new clients becomes increasingly complex. Existing clients still need attention. Business development efforts can’t slow down. Administrative work continues to pile up. Advisors find themselves caught between bringing in new business and maintaining the relationships they’ve already built.
At some point, growth itself starts creating stress.
Many advisors initially assume the problem is straightforward. They need another hire to increase capacity and provide more support.
Sometimes they’re right. More often, however, capacity is only part of the story.
What I frequently discover is that advisors have built practices that require them to be involved in nearly everything. Too many client questions, decisions, meetings, and service requests still find their way back to them.
They’ve become the center of every process.
When that happens, growth creates a bottleneck because the business can only move as fast as one person can move.
In my experience, advisors can even begin losing clients despite successfully bringing in new ones. The issue isn’t a lack of demand. It’s that the systems, structure, and service model haven’t evolved alongside the business.
The practice is growing, but it isn’t scaling. Before advisors can redesign the business, they need clarity about what they’re designing it to accomplish.
When advisors come to me looking for solutions, they are often surprised by where we start.
We don’t begin with organizational charts or staffing plans.
We begin with values.
I ask advisors to identify what matters most to them and then narrow those values down to the handful that truly guide their decisions. From there, we move into bigger questions.
This process helps create clarity around something many advisors haven’t stopped to consider: your business should support the life you want to build, not dictate it.
I call this “Life by Design.”
Too often, advisors become so focused on maintaining the practice that they lose sight of why they built it in the first place. Revisiting values provides an opportunity to step back, reassess, and make more intentional decisions about the future.
One of the most powerful moments in this process happens when advisors look at their client base through a different lens.
Many initially evaluate client relationships primarily through assets or revenue. But when we begin evaluating relationships based on multiple factors, including fit, engagement, advocacy, and enjoyment, the picture often changes.
We start by defining an ideal client profile. Assets matter, but they’re only one criterion. We also want to know:
Then we segment the client base and begin asking hard questions.
That’s often a light bulb moment.
Advisors realize some of their favorite clients aren’t generating the most revenue. They also identify relationships that require more time and attention than their current service model can sustainably support.
Most importantly, they begin to understand that not every client requires the same service model. If you have hundreds of households, you can’t be everything to everybody.
That clarity can help advisors create clearer service tiers, establish realistic expectations, and focus more energy on the relationships where they can add the greatest value for clients.
I’ve found that the advisors who successfully navigate this transition rarely do it by working harder. Instead, they begin viewing their businesses through a different lens.
They stop asking, “How can I fit more into my day?” and start asking more strategic questions:
That shift changes everything.
As advisors gain clarity around their values, ideal clients, and long-term vision, they begin making decisions more intentionally. They establish boundaries. They become more selective about where they invest their time and energy. They stop trying to connect with everyone and start focusing on the relationships and work that matter most.
Perhaps most importantly, they begin to recognize that the goal isn’t simply to create more capacity.
The goal is to create space.
Space to think strategically rather than reactively. Space to focus on high-value work. Space to develop future leaders. Space to build a business that can continue growing without demanding more and more of the founder’s time.
This is often the moment when the accidental CEO emerges.
Not because they’ve hired a team or created a formal business plan, but because they’ve stopped letting the practice dictate their life and started intentionally designing a practice that supports both their clients and their future.
In Part 2 of this series, we’ll explore what happens next: how advisors move from recognizing the need for a team to building one, and why leadership, communication, and systems become the foundation for sustainable growth.
DISCLAIMER: The Heart of Advice Blog reflects the author’s views and is meant as an educational and informative resource for financial professionals and individuals alike. It is not meant to be, and should not be taken as financial, legal, tax or other professional advice. Those seeking professional advice may do so by consulting with a professional advisor. eMoney Advisor will not be liable for any actions you may take based on the content of this blog.
The views and opinions expressed by this blog post guest are solely those of the guest and do not necessarily reflect the opinions of eMoney Advisor, LLC. The guest is affiliated with Mariner Wealth Advisors, LLC (“Mariner”). eMoney Advisor is not responsible for the content, views or opinions presented by our guest, nor may eMoney Advisor be held liable for any actions taken by you based on the content, views or opinions of the guest.
You may also be interested in...
Wealth management professionals are facing pressure on multiple fronts. While practices and firms encounter a wide range of challenges as… Read More
Serving clients across the wealth continuum requires more than strong technical planning skills and knowledge. It requires understanding how client… Read More
Most financial professionals have been told to communicate their value more effectively: highlight expertise; showcase process; explain your planning capabilities,… Read More
Download this eBook now and learn how enterprises can scale with confidence.
Download Now
a new source of expert insights for financial professionals.
Get StartedTips specific to the eMoney platform can be found in
the eMoney application, under Help, eMoney Advisor Blog.